Essay
Fund Due Diligence: A Practical Guide for Advisors
Fund due diligence is a structured review of a fund and the people behind it, done before any money is committed. It covers the manager, the strategy, the fees and terms, the performance record, the operations and the legal documents. The goal is to confirm that each material claim is backed by evidence and that the fund fits the investor it is meant for. This guide walks through that review in the order we would run it.
TL;DR
- Due diligence tests claims against evidence: the manager, strategy, terms, performance, operations and legal documents each get checked.
- Standard questionnaires from AIMA and ILPA give you a tested starting list, but the questionnaire is the first step, not the last.
- Operational risk, such as administrators, auditors, custody and valuation, is where funds most often fail, so give it its own gate.
- Real estate funds follow the same logic with added property-level and vehicle-level questions.
- Outside help is worth considering when the volume of funds or the complexity of the documents outgrows your team’s time.
Table of Contents
- What fund due diligence is meant to do
- The core review, step by step
- What a fund due diligence checklist should cover
- Why the questionnaire is only the start
- Operational due diligence: the gate that protects the rest
- Reading performance and regulatory filings
- Real estate investment and real estate fund due diligence
- Outsourcing fund due diligence
- Our perspective
- Work with us on your next fund review
- FAQ
- Sources
What fund due diligence is meant to do
The CAIA Association defines due diligence as a review of an investment with an appropriate level of competence, care, and thoroughness. Its purpose is to identify the funds most appropriate for the investor, based on the fund’s structure, its tax and legal characteristics, the manager’s strategy and proficiency, the risk measurement and control systems, and the performance profile.
The same chapter, along with SEC examination staff, points to the risks the work is built to uncover: lack of transparency, conflicts of interest, operational inadequacy, and legal document risk, such as unusual contractual provisions that put investors at a disadvantage.
Timing matters. For private market funds, CSP Global notes that the review happens before a commitment that will likely not return capital for at least seven years, and often ten or more. A weak review is hard to undo in that setting.
The need is not limited to exotic vehicles. Investopedia says all investors should do their homework, and that it matters most for hedge funds, which tend to be more complex and opaque and face less regulatory oversight than ordinary investments.
The core review, step by step
A workable process has the same shape whether you are looking at a mutual fund, a private fund or a fund of funds. Here is the sequence we use as a frame.
- Define the client need first. Write down the objective, time horizon, liquidity needs, tax position and concentration limits. Without this, you are judging a fund in the abstract.
- Screen the manager and firm. Look at background, experience, ownership, succession planning and governance.
- Test the strategy. Can the manager explain in plain words what the fund buys, why it should work, and what would make it stop working?
- Review terms and fees. Read the fee schedule, share classes, liquidity provisions and expense policy.
- Analyze performance. Look at risk-adjusted results and how they were produced, not only the headline return.
- Run operational due diligence. Verify the service providers, controls and valuation process.
- Read the legal documents. Offering documents, subscription agreements and side letters.
- Document the conclusion. Record what you verified, what you could not, and why you decided as you did.
Step 8 is the one that gets skipped. The record is what lets you explain the decision to a client, a committee or a regulator later.
What a fund due diligence checklist should cover
You do not have to invent a checklist. Industry bodies publish detailed ones, and they converge on the same themes.
The AIMA Advisor DDQ considerations list the manager’s background and experience, governance, compliance culture, risk management, alignment of interests, strategy, leverage, fees, risk-adjusted performance, transparency and reporting, fund service providers, valuation and liquidity. AIMA’s 2025 questionnaire update keeps a modular approach and refines questions on performance presentation, outsourcing and technology risk, counterparty and leverage risk, liquidity risk management, anti-money-laundering and expense disclosure, and it adds a private markets module.
For private equity and similar funds, the ILPA DDQ 2.0 is broader still. It spans 20 topics, including key person and succession risk, investment process, team, alignment of interests, fund terms, governance and compliance, track record, valuation, reporting, legal, data security and ESG.
Here is how those themes translate into a working table.
| Area | What to ask or request | What a good answer looks like |
|---|---|---|
| Manager and team | Biographies, tenure, departures, ownership, succession plan | Stable team, clear roles, a plan if a key person leaves |
| Strategy | Investment process, sourcing, constraints, leverage use | A repeatable process you can describe back in one paragraph |
| Fees and terms | Management and performance fees, expense policy, liquidity and redemption terms | Fees you can model in dollars, with no unexplained charges |
| Performance | Track record, attribution, risk-adjusted measures | Results tied to the stated strategy and verifiable against records |
| Operations | Administrator, auditor, custodian, valuation policy, compliance | Independent providers and written controls |
| Legal | Offering documents, side letters, conflicts disclosures | No surprises between the marketing deck and the contract |
| Reporting | Frequency, content, transparency of holdings | Regular reports you can reconcile to the administrator |
One practical note on documents. Investopedia suggests requesting the pitchbook, investment mandate and performance track record, and understanding the fee structure through calls with the portfolio managers. Our own guide on questions to ask before you invest puts these in plain language.
Why the questionnaire is only the start
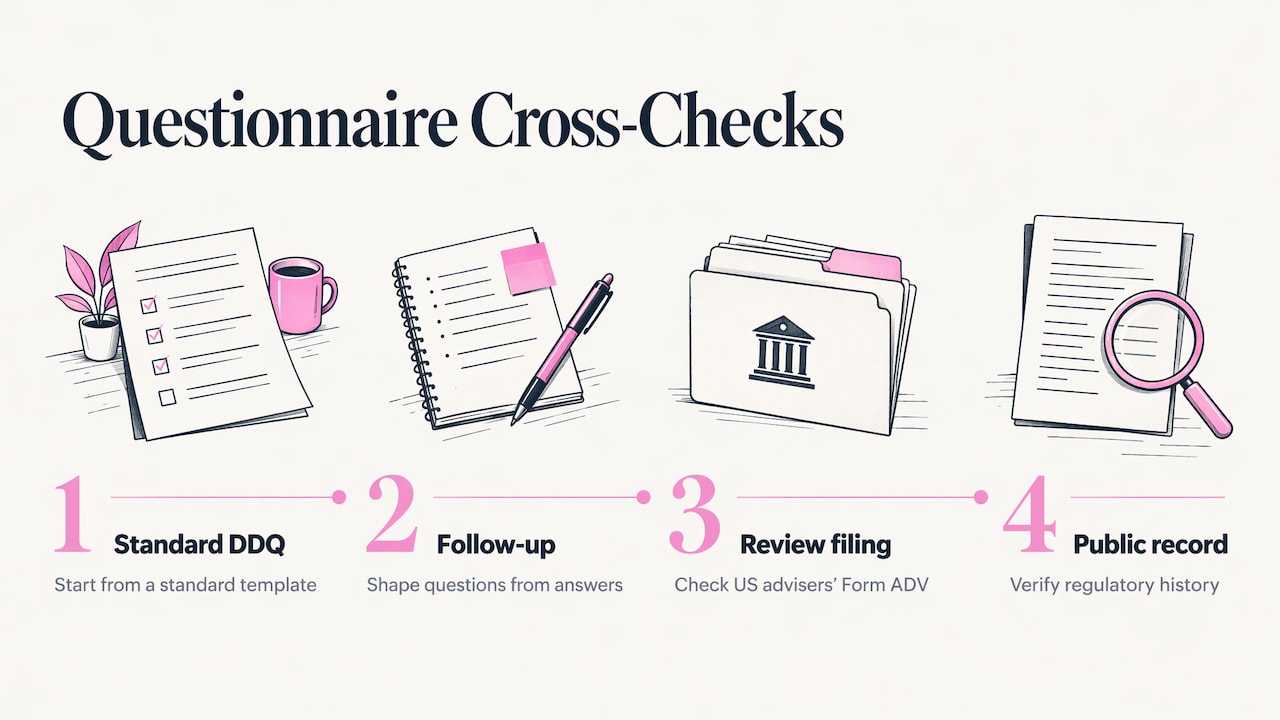
AIMA published its first DDQ for investors reviewing hedge fund managers in 1997, and the DDQs have since become an industry-standard template. AIMA is also clear that the questionnaire is an early step, by no means the last. You use the answers to shape follow-up questions and to cross-check against other sources.
That cross-checking is where most of the value sits. If a manager says the firm is registered, look at the filing. For US advisers, that means reading Form ADV, which is why we wrote a walkthrough on reading Form ADV without getting lost. If the manager describes a clean regulatory history, check the public record and our notes on securities background and disclosure explain what the entries mean.
There is an administrative reason to keep questionnaires disciplined too. ILPA observed that lengthy customized questionnaires from many parties have created an extraordinary administrative burden for everyone involved, which is why it built a standardized tool that still leaves room for investor-specific questions. Start from a standard template and add only the questions your client’s situation demands.
Operational due diligence: the gate that protects the rest
A brilliant strategy inside a badly run fund is still a bad investment. Stenham’s guide to operational due diligence says operational inadequacy is a key risk behind fund failures. The CAIA text says the same, as noted above.
The SEC’s examination staff looked at advisers that invested in or recommended private funds. Its Risk Alert of January 28, 2014 lists seven practices that give advisers more transparency:
- Using separate accounts
- Obtaining transparency reports from independent fund administrators and risk aggregators
- Verifying relationships with critical service providers
- Confirming that assets exist
- Routinely conducting onsite reviews
- Placing more emphasis on operational due diligence
- Having independent providers run comprehensive background checks
The same alert notes that the staff examined advisers who together managed approximately $2 trillion in investor assets at the time, so this is not a niche concern.
In practice, an operational review asks who the administrator and auditor are, whether they are independent of the manager, who holds the cash and securities, how hard-to-price assets are valued and by whom, and how conflicts are managed. It also covers cybersecurity, business continuity, insurance and the manager’s own anti-money-laundering procedures.
A custody rule detail worth knowing
For US-registered advisers, the custody rule offers a useful anchor. Under 17 CFR 275.206(4)-2(b)(4), a pooled vehicle can satisfy the surprise-examination requirement if it is audited at least annually by an independent public accountant registered with and inspected by the PCAOB, and the audited financial statements go to investors within 120 days of fiscal year end. If a fund you are reviewing relies on that route, ask for the audited statements and check the dates.
Reading performance and regulatory filings
Performance work is more than reading a return table. Ask how the numbers were calculated, over what period, with what leverage, and how they compare with the strategy’s own risk limits. The SEC noted that advisers had increased their use of quantitative risk measures to supplement investment-level decisions. Quantitative tools help, but they do not replace the qualitative review of the team and the process.
For registered funds, the SEC publishes how it reviews disclosure. The Division of Investment Management takes a risk-based approach, focusing more on novel and complex funds, new disclosures, and disclosures that influence decisions, such as strategies, risks, fees and performance. Those are the same sections you should read most closely yourself. If you are comparing share classes of a registered fund, our practical guide to share classes and fees shows how the same portfolio can cost very different amounts depending on the class.
Real estate investment and real estate fund due diligence
Real estate adds a physical asset layer. Buying a property directly means title, zoning, environmental condition, leases, rent rolls, taxes and physical inspection. A real estate fund wraps those questions inside a vehicle, so you do both: you assess the properties or the strategy for acquiring them, and you assess the manager and the structure.
For non-listed vehicles, INREV’s Due Diligence Questionnaire, first launched in April 2007 and updated in 2018, uses three phases: Preliminary, Advanced and Supplementary, with a vehicle fact sheet and an investment manager statement at the front. That phasing is a good habit anywhere. Use a short first pass to decide whether the fund merits the cost of a deeper review.
Additional questions for a real estate fund usually include:
- How are properties appraised, and how often?
- How much leverage sits at the property level and at the fund level?
- What are the redemption or exit terms if values fall?
- Who manages the assets day to day, and how are they paid?
- How concentrated is the portfolio by region, tenant or property type?
Outsourcing fund due diligence
Many advisory teams and institutions reach a point where the number of funds, the length of the documents and the time available do not match. That is when outside support makes sense: an independent reviewer collects documents, reads the offering materials, prepares comparison summaries and flags open items for your decision.
What stays with you is the judgment. You remain responsible for the recommendation, so whoever helps should work to your client’s objectives and show their work. Look for a clear scope in writing, documented sources for each finding, and plain explanations you can pass on to a client. Our approach to fund distribution is built on that same principle: the right fund, at the right time, with the right documentation.
Our perspective
Most due diligence problems we see are not about missing intelligence. They are about missing translation. The documents exist, the filings are public, and the questionnaires are standard. What is often absent is someone who will explain what the fee table means for a specific client, or why a footnote in an offering document changes the picture.
We believe in a simple discipline. Every material claim gets a piece of evidence, and anything we cannot verify gets written down as an open item rather than quietly dropped. With more than fifteen years in the industry, we have found that clients value that record as much as the conclusion, because it lets them show their own diligence to anyone who asks.
We also think relationships matter more than transactions. Working with advisors and institutions in Connecticut, we would rather spend an hour making sure you understand share classes, fees and regulatory filings than hand you a report full of jargon.
Sean
Work with us on your next fund review
If you are an advisor, institutional team or local business that needs a fund reviewed, we provide personalized guidance on product selection, due diligence processes, fund documentation and education about fees, share classes and regulatory filings. Start with how we think about fund distribution, then get in touch with a description of the fund and the client need.
You can also review our professional experience and see how our Connecticut work fits your situation.
FAQ
What is the difference between fund due diligence and operational due diligence?
Fund due diligence is the whole review: manager, strategy, terms, performance, operations and legal documents. Operational due diligence is the part that checks how the fund actually runs, including administrator, auditor, custody, valuation and compliance. Operational weaknesses are a leading cause of fund failures, so it deserves its own gate.
Which documents should I request first?
Start with the offering document, the investment mandate, the pitchbook, the performance track record and the fee schedule. Then request the manager’s Form ADV, audited financial statements and a completed standard questionnaire such as AIMA’s or ILPA’s. Use the answers to decide what to ask next.
Is a standard questionnaire enough?
No. AIMA describes the questionnaire as an early step in the process. Use it to organize your questions, then cross-check the responses against public records, filings and independent sources, and follow up in conversation with the manager.
Does real estate fund due diligence differ from other funds?
The structure is the same, but you add property-level questions such as valuation, leverage, tenancy and concentration. For non-listed vehicles, INREV’s phased questionnaire is a helpful model.
Sources
- CAIA: Due Diligence of Fund Managers
- CSP Global: Research insights into fund due diligence
- Investopedia: Hedge Fund Due Diligence
- AIMA: Advisor DDQ Considerations
- AIMA: The 2025 Edition of the Illustrative Questionnaire
- AIMA: Due Diligence Questionnaires
- ILPA: Due Diligence Questionnaire 2.0
- SEC: Risk Alert on Investment Adviser Due Diligence Processes
- SEC: Fund Disclosure at a Glance
- eCFR: 17 CFR 275.206(4)-2
- INREV: Due Diligence Questionnaire for Non-Listed Real Estate Investment Vehicles